From your VIN to a documented number
Why the report is the number to send
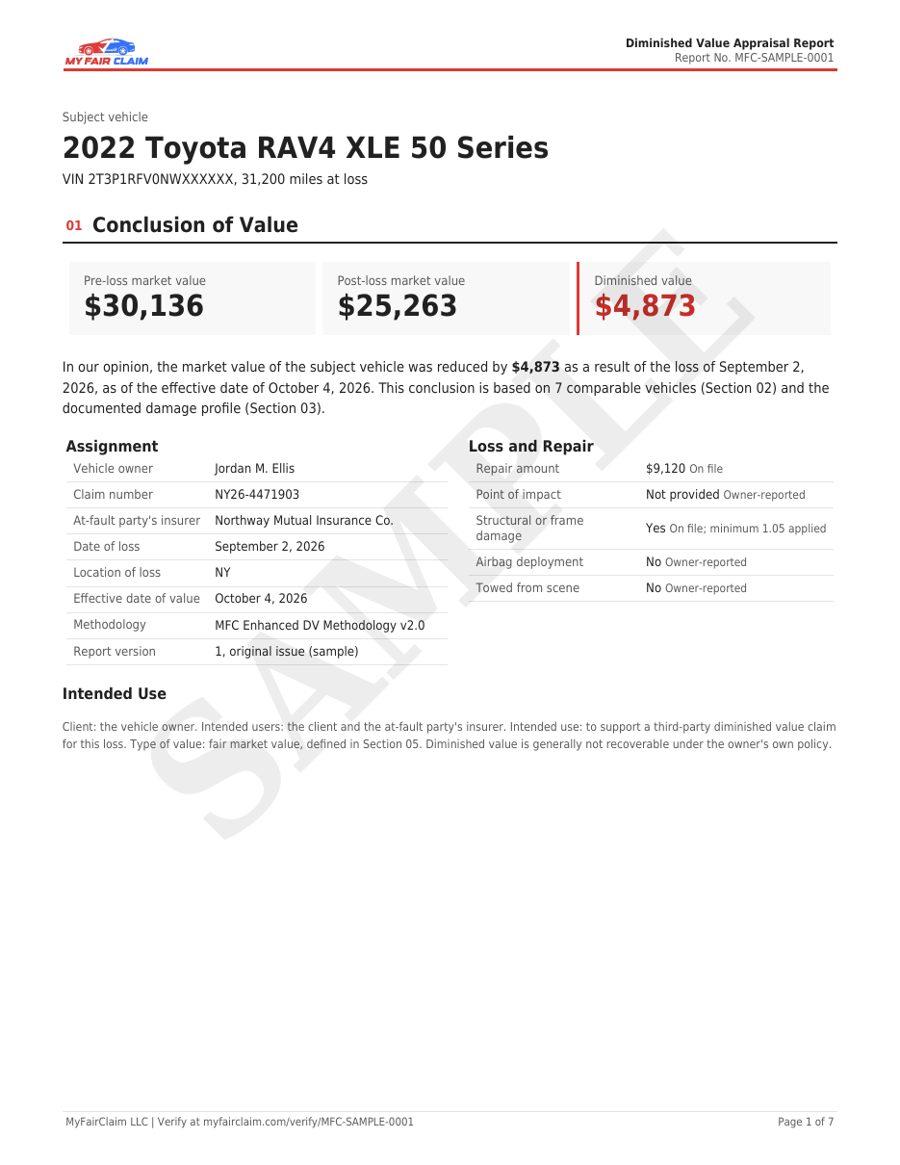
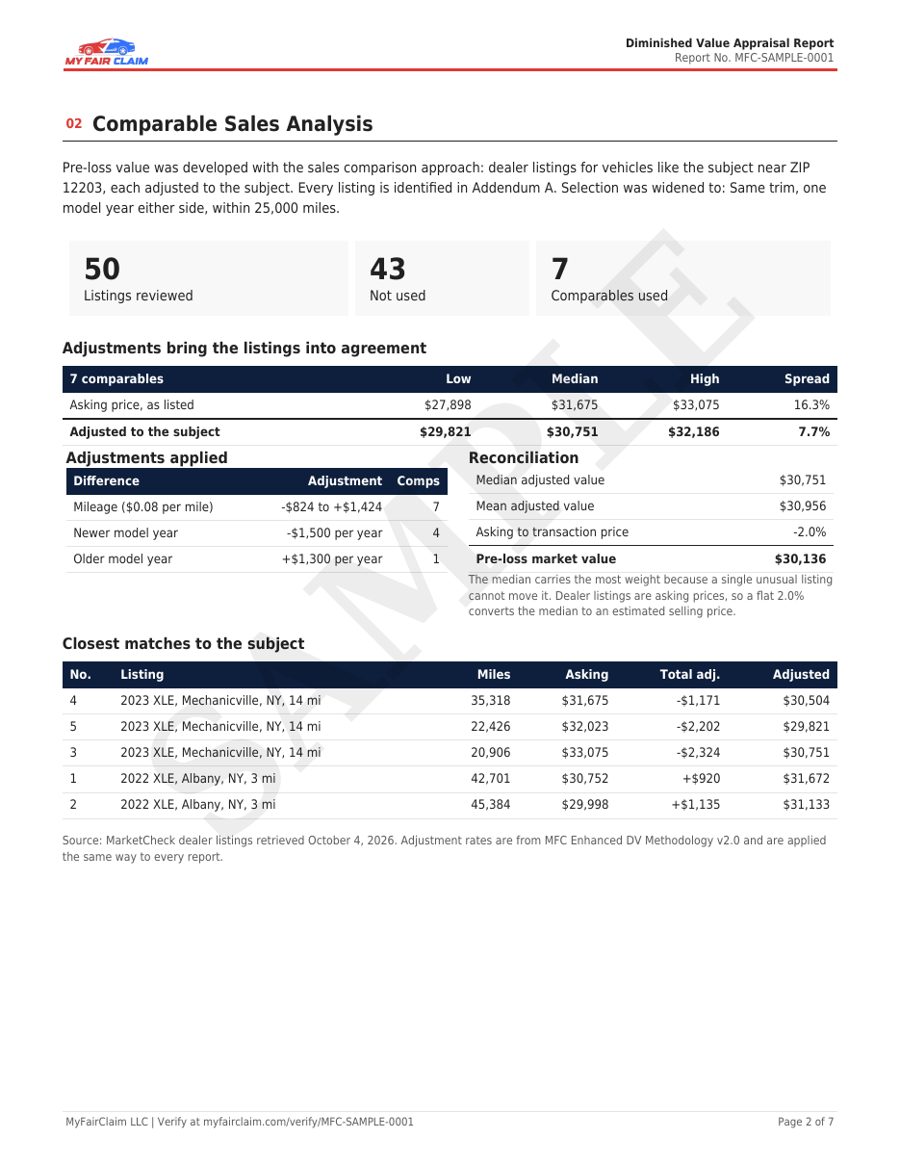
The free calculator works only from what you tell it: your car's value, mileage at the time of the accident and damage level, plus the date of loss and repair amount if you add them. With a date of loss, it moves the value you enter to that date using the government's used car price index. It prices the least favorable case within each answer, so the range is deliberately conservative. Your report replaces your answers with real comparable sales for your exact vehicle, your actual repair details and a documented loss calculation. As long as your car and damage match what you entered, it will not come in below the free estimate.
Where the numbers come from
Every month we run this same method on current listings for popular used cars and publish the results on our diminished value data page.
Is this a USPAP appraisal?
No, and it isn't meant to be. USPAP (the Uniform Standards of Professional Appraisal Practice) is the rulebook a licensed appraiser follows when they personally prepare an appraisal: they research the vehicle, choose comparables by hand and write up their own opinion of value. That usually takes days and costs $250 to $600.
MyFairClaim works differently. It's an automated valuation system: one published method, applied the same way to every car, using current dealer listings matched to your vehicle. Every comparable, adjustment and calculation is shown in the report, automatic checks run on every report and a member of our team reviews any report they flag, and anyone can check a report with its report number. Most reports are ready in minutes.
Does it matter for my claim?
For most claims you settle directly with the insurer, nothing requires a USPAP appraisal. What moves an adjuster is evidence they can check: real comparable vehicles, stated adjustments and a clear number. That is what the report gives you.
When you may want a licensed appraiser
If your claim goes to court, an attorney asks for a credentialed appraiser's opinion, or you invoke your policy's appraisal clause, you may need a licensed appraiser. Your report still helps: it gives them the market data to start from.
The honest limits